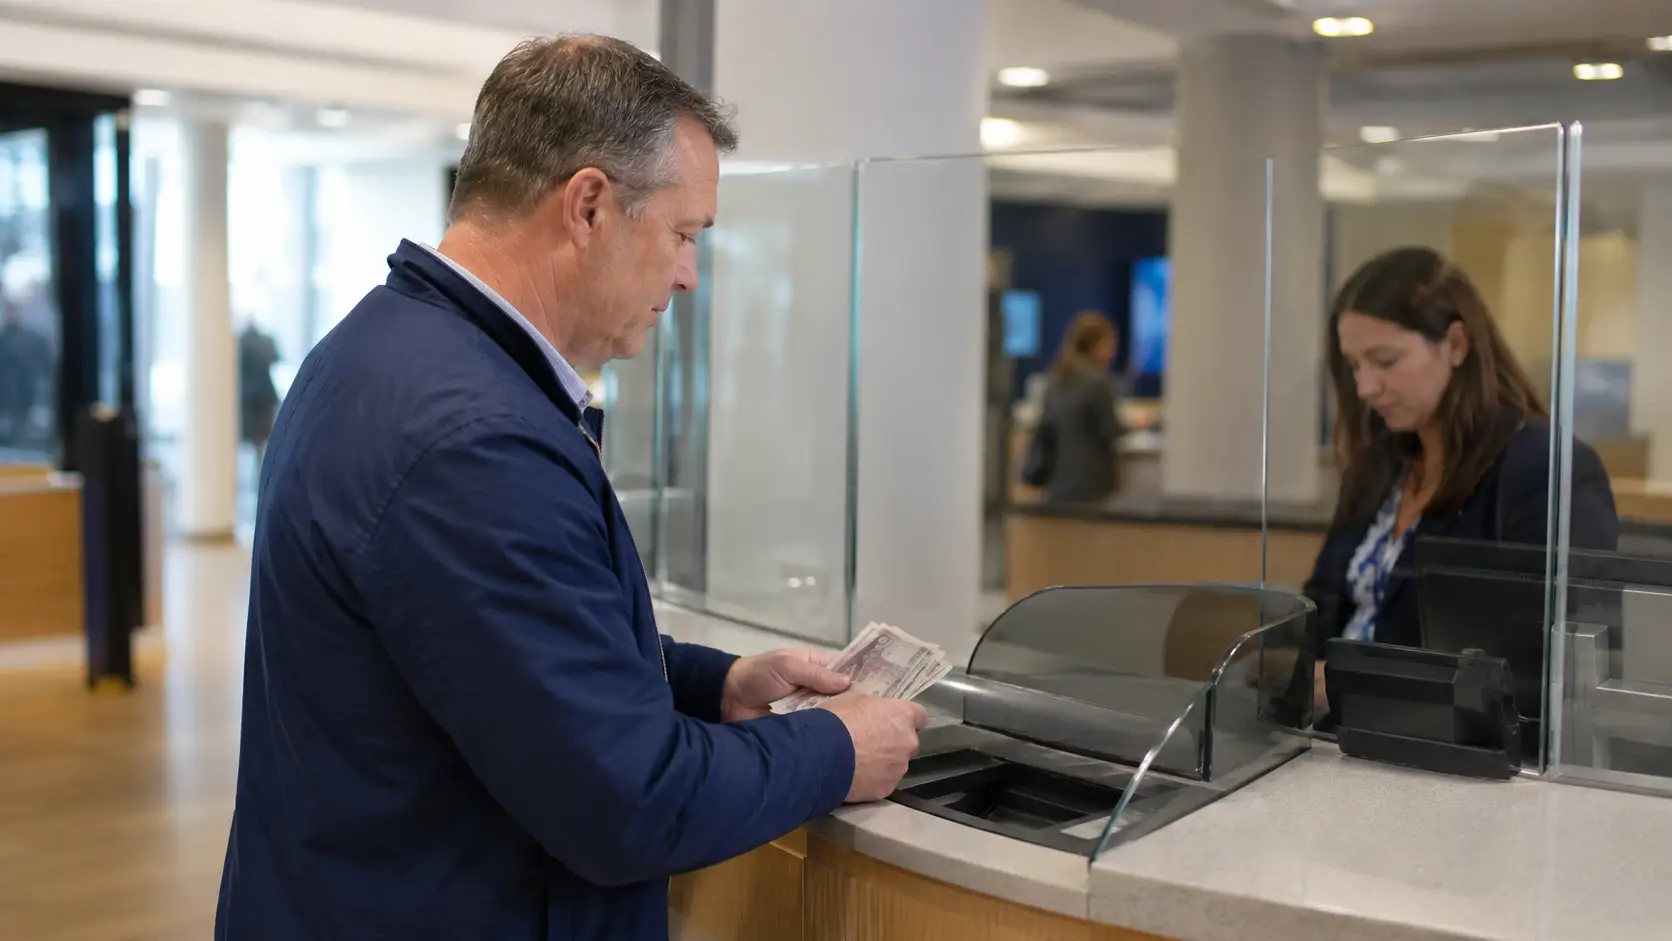
There is no universal amount of cash that a person can deposit without raising suspicion in the UK.
UK banks do not operate one publicly stated “safe” cash-deposit threshold.
Instead, they use a risk-based approach that considers the amount being deposited, how often cash enters the account, where the money came from, the customer’s normal account activity, occupation or business, and whether the transactions make financial sense.
Someone may legitimately deposit £10,000, £20,000 or more where the money has a clear and documented source.
By contrast, repeated unexplained deposits of much smaller amounts can attract additional scrutiny when they do not match the customer’s known income or usual banking activity.
The key distinction is between:
- A bank’s deposit limit: How much cash the institution permits through a branch, ATM, Cash Deposit Machine, Post Office or other channel.
- An anti-money-laundering threshold: There is no single published UK amount below which a cash deposit is guaranteed to avoid checks.
- A tax issue: Depositing cash does not itself make the money taxable. Tax depends on where the money came from.
The safest approach is therefore not to try to remain underneath an assumed reporting limit. It is to deposit legitimate money transparently, keep evidence of its source and comply with the limits imposed by the bank.
Is There a Legal Cash Deposit Limit Before a Bank Becomes Suspicious?
No UK law provides a general cash amount that guarantees a deposit will be accepted without questions.
Banks, building societies and other regulated financial businesses must monitor transactions and relationships for financial-crime risks.
That can involve assessing:
- Whether the amount is normal for the account
- Whether it matches the customer’s known occupation or income
- Whether cash levels make sense for the type of business involved
- Whether deposits have suddenly increased
- Whether another person is supplying the cash
- Whether cash is quickly transferred elsewhere
- Whether a large amount has been divided into numerous smaller deposits
- Whether the customer’s explanation changes
- Whether reliable source-of-funds evidence exists
A restaurant depositing several thousand pounds of legitimate weekly cash takings may therefore present a different risk profile from a salaried employee whose account has never previously received cash but suddenly receives repeated unexplained deposits.
The amount is only one part of the assessment.
What Are the Cash Deposit Limits at Major UK Banks?
Bank deposit limits are not the same as suspicion or reporting thresholds.
They are limits imposed by individual banks for particular accounts and deposit methods. They can also change, meaning anyone planning a substantial cash deposit should check their account’s current rules beforehand.
The following examples reflect published limits available in September 2026.
| Bank | Account or Channel | Published Cash Deposit Limit |
|---|---|---|
| NatWest | Post Office or Cash & Deposit Machine | £3,000 daily; £24,000 over a rolling 12 months |
| NatWest | Branch counter | £3,000 daily, with a higher £50,000 rolling annual branch-counter limit |
| Royal Bank of Scotland | Post Office or CDM | £3,000 daily; £24,000 over a rolling 12 months |
| Royal Bank of Scotland | Branch counter | £3,000 daily, with a £50,000 rolling annual branch-counter limit |
| HSBC Business | Self-service deposit | Up to £9,000 a day and £40,000 a month |
| HSBC Business | Combined self-service/Post Office activity | A shared daily cash limit can also apply across deposit channels |
| Barclays Personal | Across personal cash deposits | £20,000 annual cash-deposit limit |
| Barclays Personal | Post Office | A separate £10,000 Post Office cash-deposit limit applies |
| Santander Business | Post Office | £10,000 daily and £240,000 rolling annual limit |
| Santander | Some personal/Select Post Office services | Published limits can permit up to £20,000, depending on the account and location |
| Nationwide Personal | Nationwide cash machine | £2,500 per day |
| Nationwide Personal | Branch counter | Up to £20,000, subject to the annual limit |
| Nationwide Personal | Total personal cash deposits | £20,000 per year |
| Nationwide Personal | PayPoint | £300 per day |
These figures show why searching for one universal answer to “how much cash can I deposit?” can be misleading.
A customer may be legally entitled to the money but still be unable to pay the whole sum through a particular ATM, Post Office or bank branch.
Banks can also impose different limits on:
- Personal accounts
- Joint accounts
- Sole trader accounts
- Limited-company accounts
- Cash-intensive businesses
- Individual customers considered higher risk
The published limit should therefore be treated as the starting point rather than a promise that every deposit will be accepted without additional checks.
Do ATM and Cash Deposit Machine Limits Work Differently?
Yes.
An ATM or Cash Deposit Machine, commonly called a CDM, can have both a monetary limit and a physical note limit.
For example, a machine might accept only a set number of banknotes in one transaction even where the customer’s daily cash-deposit allowance has not been reached.
This can produce several different restrictions:
- Maximum value per transaction
- Maximum number of notes per transaction
- Maximum value per day
- Monthly deposit limit
- Rolling annual cash limit
- Restrictions on coins
- Restrictions on third-party cash deposits
NatWest CDMs, for example, can accept up to 50 notes in one deposit while the bank’s wider cash-deposit limits continue to apply.
Using the machine repeatedly does not necessarily create a new allowance. Deposits are normally counted towards the applicable daily or annual customer limit.
Is £5,000 the Amount Banks Start Questioning?
Not as a universal rule.
The figure of £5,000 is commonly repeated in UK anti-money-laundering discussions, and some compliance specialists state that banks commonly request source-of-funds evidence when deposits exceed this level.
However, there is no general UK law saying:
“Cash deposits below £5,000 are safe and deposits above £5,000 must be reported.”
That interpretation should be avoided.
A bank could ask questions about £2,000 if the transaction is unusual for the customer. It may accept a much larger transaction where its origin is clear, the activity is consistent with the customer’s profile and reliable evidence is available.
The £5,000 figure is therefore better understood as a commonly referenced practical point, not a statutory reporting line or guaranteed threshold.
What Are Structuring and Smurfing?
Splitting large amounts of cash into smaller deposits is sometimes described using the terms structuring and smurfing.
Structuring
Structuring generally describes one person deliberately dividing a larger amount into smaller deposits in an attempt to reduce scrutiny or avoid financial-crime controls.
For example, someone holding £18,000 might make a series of £2,000 or £3,000 deposits because they believe staying below a certain number prevents detection.
Banks can analyse transaction patterns, so the series itself may become more unusual than one properly documented deposit.
Smurfing
Smurfing generally involves spreading deposits across several individuals or accounts.
Different people may deposit smaller portions before the funds are later consolidated.
The important point for legitimate bank customers is simple: do not artificially divide legitimate money purely to avoid questions.
A clear audit trail is usually easier to explain than numerous deliberately fragmented transactions.
Is the UK £10,000 Rule the Same as the US Cash Reporting Rule?
No.
A major reason the £10,000 figure appears in online discussions is confusion with the United States.
US banking rules include a Currency Transaction Report system under which certain cash transactions exceeding $10,000 in a business day must be reported.
The UK does not simply copy that model for ordinary bank deposits.
UK financial institutions instead operate a broader suspicion-based anti-money-laundering regime.
This means:
- £9,999 is not automatically “safe”
- £10,000 is not automatically illegal
- £20,000 is not automatically money laundering
- A smaller pattern of unexplained deposits can still be scrutinised
Trying to engineer deposits around a supposed threshold misunderstands how UK transaction monitoring works.
How Much Cash Can You Deposit at a Post Office?
The Post Office provides cash-deposit facilities for customers of many UK banks.
Its own physical counter limits can differ depending on the type of counter and the service available, while the customer’s bank can impose a considerably lower account limit.
A Post Office counter being physically capable of processing a substantial amount does not mean that a particular customer’s bank permits that amount.
For example, one bank might allow £10,000 while another may restrict the customer to £3,000 per day.
Before travelling with a significant amount of cash:
- Check the bank’s current deposit limit.
- Check whether the particular Post Office can process the amount.
- Ask whether advance notice is required.
- Take the appropriate bank card or deposit card.
- Retain the transaction receipt.
Businesses depositing particularly large takings may need a specialist cash-handling arrangement rather than repeated counter deposits.
Can Cash Be Deposited Through a Banking Hub?
Yes, where the customer’s bank participates in the relevant services.
Banking Hubs have become increasingly important as traditional branches close.
A Banking Hub is a shared banking location with a counter operated by the Post Office. Customers of participating major banks can generally carry out routine cash services there.
Typical counter services include:
- Paying in notes
- Paying in coins
- Depositing cheques
- Withdrawing cash
- Checking an account balance
- Obtaining change for eligible businesses
The key limitation remains the customer’s bank limit.
A Banking Hub does not override a bank’s normal cash-deposit restrictions simply because it provides a physical counter.
Customers depositing large amounts should therefore still check the applicable limit before attending.
Can You Deposit Cash Into Monzo, Starling, Tide or Revolut?
Digital and challenger banks handle physical cash differently from traditional branch banks.
Some use Post Office or PayPoint networks, while others do not currently support cash deposits at all.
Monzo
Monzo personal customers can deposit cash through both the Post Office and PayPoint.
For personal accounts, the published cash-deposit limit is currently £750 per month.
At the Post Office, up to £750 can be deposited in a single transaction within the monthly allowance.
At PayPoint, an individual transaction can be up to £300, again subject to the £750 monthly limit.
Standard cash deposits normally carry a £1 fee, although some paid Monzo plans include a number of free monthly deposits.
Monzo’s business limits are higher:
- Sole Trader Business Account: up to £3,000 per calendar month
- Limited Company Business Account: up to £10,000 per calendar month
Starling Bank
Starling personal and joint customers can deposit cash through the Post Office.
The standard published personal limit is:
- Up to £1,000 per day
- Up to £5,000 per calendar year
- No more than £250 of a daily deposit in coins
The first £1,000 deposited during a calendar year is currently free, after which a percentage charge applies.
Starling business customers have substantially higher allowances. Published limits can reach £5,000 per day, with different annual caps for business and sole-trader accounts.
Tide
Tide permits cash deposits through the Post Office and PayPoint.
For Post Office deposits, Tide currently publishes limits of:
- £25,000 per single deposit
- £25,000 per month
- £300,000 per year
Charges depend on the customer’s plan and the amount deposited.
Tide therefore provides much greater cash capacity than many personal-focused app banks, although it is designed primarily around business banking.
Revolut
Revolut previously introduced cash deposits for some UK customers but discontinued the service from 13 February 2026.
Customers currently need to add money using supported alternatives such as bank transfers, debit cards or eligible digital-payment methods rather than physical cash.
The differences between these providers show why “digital bank” should not be treated as one category with one cash policy.
Why Does a Bank Care Where Cash Came From?
Physical cash has less built-in transaction history than an electronic bank transfer.
A bank may therefore need to establish the source of funds.
Possible legitimate sources include:
- Business sales
- Cash wages paid lawfully through payroll
- Selling a vehicle
- Selling jewellery or another valuable possession
- An inheritance
- A family gift
- Previously withdrawn savings
- Insurance compensation
- A private loan
- Sale proceeds from an investment or asset
Questions about cash gifts often overlap with separate tax and inheritance issues. UK Business Times has a detailed explanation of whether cash gifts need to be declared to HMRC.
The bank asking for evidence does not automatically mean it believes the customer committed an offence.
The institution may simply be carrying out customer due diligence or responding to an automated transaction-monitoring alert.
What Types of Cash Deposits Can Attract More Scrutiny?
No single factor proves wrongdoing. Banks generally look at combinations of indicators.
Deposits That Do Not Match the Customer’s Profile
A salaried worker who usually receives £2,500 through PAYE each month may attract questions after suddenly depositing £25,000 cash.
A restaurant with a documented history of substantial cash takings might be expected to make considerably larger deposits.
Context matters.
Repeated Deposits Just Below an Assumed Threshold
Repeated amounts such as £4,900 or £9,900 can appear more unusual where they seem deliberately designed to remain below a believed threshold.
Artificial splitting should therefore not be used as a method of avoiding questions.
Cash Immediately Moved Elsewhere
Depositing cash and transferring it away immediately can receive additional scrutiny where no clear commercial explanation exists.
Third-Party Cash Deposits
Cash supplied by someone other than the account holder can be harder for a bank to understand.
The bank may ask:
- Who supplied it?
- Why was the money given to the customer?
- Who ultimately owns it?
- What transaction generated it?
Explanations That Change
A lack of perfect paperwork does not automatically make money unlawful.
However, contradictory explanations or documents created purely to support a false story can create significantly more concern.
Customers should never invent invoices, receipts, loan documents or sale agreements.
Are Cash Rules Different for Personal and Business Accounts?
The same broad anti-money-laundering principles apply, but normal behaviour can differ substantially.
Personal Accounts
Legitimate occasional cash deposits can arise from:
- Selling a car
- Family gifts
- Inheritance
- Wedding gifts
- Personal savings kept at home
- Insurance settlements
- Lawfully paid cash wages
A very large deposit may still require additional documentation.
Repeatedly putting business takings into a personal account can also create problems because the activity may conflict with the account terms.
Business Accounts
A cash-intensive company should ensure its bank understands how the business operates.
The institution may compare cash deposits with:
- Expected turnover
- Previous deposits
- Industry type
- Card sales
- Declared business activity
- Accounting information
- Information supplied when the account was opened
A major increase in cash turnover should have a commercial explanation.
For example, a restaurant that launches a second location could reasonably see its deposits increase. A supposedly online-only consultancy suddenly paying in thousands of pounds of banknotes every week may generate more questions.
What Documents Can Prove the Source of Cash?
Useful evidence depends on the transaction.
| Source | Possible Evidence |
|---|---|
| Business takings | Till reports, invoices, cashbook, accounts, VAT records |
| Vehicle sale | Advertisement, signed receipt, buyer correspondence, vehicle-transfer records |
| Private item sale | Original purchase records, advertisement, buyer messages, signed receipt |
| Inheritance | Probate documents, estate correspondence, solicitor records |
| Gift | Gift letter, donor bank statements and evidence of donor's source |
| Cash wages | Payslips, payroll records, employer correspondence |
| Insurance payment | Insurer settlement documents |
| Loan | Signed loan agreement and evidence showing lender's source |
| Old personal savings | Historical statements, previous withdrawals, earnings records |
| Property transaction | Solicitor completion statement and transaction documentation |
Evidence should match the dates, parties and amounts involved.
A document labelled “receipt” is less useful if the dates or transaction values contradict the bank deposit.
What Happens When a Bank Questions a Cash Deposit?
The process varies between banks.
The institution might:
- Ask the customer where the cash came from.
- Ask why it is being deposited.
- Request documents.
- Refer the transaction for an internal financial-crime review.
- Refuse the cash if an operational limit has been exceeded.
- Restrict a transaction or account temporarily.
- Decide it no longer wishes to provide the banking relationship.
- Submit a Suspicious Activity Report where appropriate.
Being questioned is not the same as being found guilty of money laundering.
Banks are required to manage financial-crime risk and may need further information before being satisfied.
What Is a Suspicious Activity Report?
A Suspicious Activity Report, or SAR, is intelligence submitted to the UK Financial Intelligence Unit within the National Crime Agency.
Regulated organisations can have reporting obligations when they know or suspect money laundering or terrorist financing.
A SAR itself does not prove the customer committed a crime.
The bank may also be restricted in what it can tell the customer. UK law contains provisions intended to prevent disclosures that could prejudice an investigation, commonly referred to in discussions of “tipping off”.
That is one reason bank staff may sometimes provide limited information while an account or transaction is being reviewed.
Can a Cash Deposit Lead to an Account Freezing Order?
Potentially, but an Account Freezing Order is much more serious than an ordinary bank compliance check.
An Account Freezing Order, or AFO, is a civil asset-recovery power under the Proceeds of Crime Act framework.
Relevant enforcement officers can apply to a court where there are reasonable grounds to suspect that money in a qualifying account represents recoverable property or is intended for use in unlawful conduct.
Important features include:
- The qualifying amount is currently at least £1,000.
- A criminal conviction is not required before an AFO can be granted.
- Orders can be granted for periods of up to six months at a time.
- The overall freezing period can extend to a maximum of two years.
- The order prevents the money being withdrawn or otherwise used except where permitted.
- A person affected by the order can apply for it to be varied or set aside.
- A court can make exclusions allowing specified payments in appropriate circumstances.
An ordinary temporary bank restriction is therefore not necessarily an Account Freezing Order.
The latter involves formal legal proceedings and court powers.
Does Depositing Cash Automatically Trigger an HMRC Investigation?
No.
Putting cash into a bank account does not automatically notify HMRC that tax has been evaded.
However, the underlying source of the cash can matter significantly.
Examples include:
- Cash customer payments that form part of taxable business turnover
- Rental income received in cash
- Undeclared self-employment income
- Taxable gains
- Company money taken personally
- Overseas income
- Previously undeclared taxable earnings
By contrast, depositing previously taxed savings or a genuine non-income gift does not become taxable merely because the money enters a bank.
Where HMRC receives information suggesting undeclared income, it can undertake compliance activity.
Readers wanting more context on the investigative stages can see what happens when someone is reported to HMRC.
What Is HMRC’s Connect System?
HMRC operates an analytical system known as Connect.
Connect allows HMRC to cross-reference very large volumes of information from different sources.
Data can include information connected with:
- Self Assessment
- Property
- Financial records
- Companies
- Employment
- Tax declarations
- International financial-information exchanges
HMRC has previously described Connect as cross-referencing more than 22 billion lines of data.
Its significance is that HMRC does not necessarily need to examine one bank deposit in isolation.
It can identify inconsistencies between different information sources.
For example, someone repeatedly declaring very little taxable income while acquiring valuable assets or receiving financial inflows inconsistent with the declared position may attract compliance interest.
Connect does not mean every unusual transaction automatically generates an investigation. It is a risk-analysis and data-matching tool.
Can HMRC Obtain Bank Information Using a Financial Institution Notice?
Yes.
HMRC has a specific power known as a Financial Institution Notice, commonly abbreviated to FIN.
A FIN can require a bank or another qualifying financial institution to provide information HMRC reasonably requires for purposes such as:
- Checking a known taxpayer’s tax position
- Collecting a tax debt
An important feature is that HMRC does not have to obtain advance approval from the taxpayer or the independent tax tribunal before issuing a FIN.
Internal authorisation and statutory safeguards still apply.
Normally, the taxpayer must also be identified and provided with appropriate information about the notice, although there are circumstances where a tribunal can disapply particular notification requirements.
A FIN should therefore not be confused with banks automatically sending HMRC every cash deposit above a particular amount.
It is a statutory information-gathering power that HMRC can use in appropriate tax cases.
Is There a Real Example of HMRC Challenging Unexplained Bank Deposits?
Yes.
A useful example is Akhtar v Revenue and Customs [2025] UKFTT 395 (TC).
The case involved a taxpayer associated with taxi businesses and HMRC discovery assessments totalling approximately £350,000.
One major issue was the source of substantial deposits appearing in bank accounts.
The taxpayer argued that various amounts came from friends or relatives. HMRC maintained that significant amounts represented undeclared money connected with the businesses.
The First-tier Tribunal considered extensive evidence rather than simply assuming every deposit represented taxable income.
It ultimately found that the taxpayer had failed to provide a satisfactory explanation for approximately £220,000 of bank deposits.
However, the tribunal also accepted evidence that third parties had provided money towards certain property purchases.
That distinction matters.
The case does not establish that “large deposits are automatically taxable”. Instead, it demonstrates the importance of being able to substantiate claims about where significant sums came from.
Where a taxpayer says money came from a friend, relative, loan or other non-taxable source, contemporaneous independent evidence can become crucial years later.
How Should You Deposit a Large Amount of Legitimate Cash?
Someone holding a substantial amount of legitimate cash should focus on transparency rather than trying to avoid attention.
A practical approach is to:
- Check the account’s deposit limit: Confirm the current daily, monthly and annual caps.
- Check the deposit channel: A branch, ATM, CDM, Post Office and Banking Hub may have different limits.
- Contact the bank in advance: Particularly when the amount is substantially outside normal account activity.
- Prepare evidence: Bring documents explaining where the money came from.
- Use the correct account: Business income should normally be handled through an appropriate business account.
- Keep the receipt: Retain proof showing when and where the cash was paid in.
- Update accounting records: Businesses should make sure the deposit reconciles with sales and tax records.
- Answer questions accurately: Do not exaggerate or invent an explanation because paperwork is incomplete.
- Do not deliberately fragment the deposit: Artificial structuring can create an additional financial-crime indicator.
A customer with legitimate money does not need to make the transaction look artificially smaller.
They need to be able to explain it.
FAQs
How much cash can you deposit into a UK bank at once?
It depends on the bank, account and deposit method. There is no universal legal maximum applying to every UK account.
Will a bank question a £5,000 cash deposit?
It might, but £5,000 is not a universal reporting threshold. The bank will consider whether the transaction fits the customer’s normal financial activity and whether its source can be explained.
Is depositing £10,000 cash suspicious?
Not automatically. A documented £10,000 vehicle sale could be legitimate, while repeated unexplained smaller deposits may receive more scrutiny.
Is depositing £20,000 cash illegal?
No. The legality depends on the source of the money, although a bank’s operational limits may prevent £20,000 being deposited through a particular channel.
Do UK banks automatically report deposits over £10,000?
There is no general UK rule requiring every ordinary cash deposit above £10,000 to be automatically reported simply because it crosses that amount.
What is structuring in banking?
Structuring is the deliberate splitting of a larger amount into smaller transactions, commonly in an attempt to reduce scrutiny or avoid financial controls.
What is smurfing?
Smurfing usually involves dividing money between multiple people or accounts before the funds are eventually consolidated or moved elsewhere.
Can HMRC see large cash deposits?
HMRC does not automatically receive every large cash deposit as a special threshold report. However, it has extensive information-gathering and data-matching powers and may obtain financial information during a tax investigation.