Missing a Universal Credit appointment does not automatically mean a claimant will be sanctioned. The Department for Work and Pensions (DWP) considers whether there was a good reason for failing to attend or participate.
Unexpected illness, a hospital appointment, bereavement, a domestic emergency, serious caring problems, transport disruption and similar unavoidable circumstances may all be relevant.
The strongest explanations normally have three features: the problem was outside the claimant’s reasonable control, it directly prevented attendance or participation, and Universal Credit was told as quickly as reasonably possible.
Supporting evidence can make that explanation stronger, but every case is considered individually.
What Counts as an Acceptable Reason for Missing a Universal Credit Appointment?
There is no official list of circumstances that Universal Credit must automatically accept.
Instead, the DWP considers whether the claimant had a good reason for failing to meet the particular requirement.
Current GOV.UK guidance specifically gives examples including:
- Having a hospital appointment at the same time as the Universal Credit meeting
- Becoming unexpectedly ill and being unable to complete a work-related activity
- Having a domestic emergency that prevents attendance.
The circumstances surrounding the problem are therefore as important as the name given to the reason.
A Simple Three-Part Test for a Good Reason
A claimant can make the situation easier to assess by asking three questions:
| Question | What the DWP Needs to Understand |
|---|---|
| Was the situation outside reasonable control? | Was it genuinely unexpected, unavoidable or difficult to prevent? |
| Did it actually stop attendance? | How did the problem prevent the claimant travelling, answering the phone or participating online? |
| Was Universal Credit told promptly? | Did the claimant make contact before the appointment where possible, or as soon as reasonably possible afterwards? |
A reason becomes more persuasive when all three points can be explained clearly.
For example, simply stating “transport problems” gives little information.
Explaining that the final available train was cancelled, no alternative service was available and a journal message was sent as soon as the cancellation was confirmed gives the decision-maker a much clearer sequence of events.
Is It Called a “Good Reason” or “Good Cause”?
For Universal Credit, “good reason” is the more accurate current term.
The expression “good cause” is still found in older benefit information and discussions relating to legacy benefits such as Jobseeker’s Allowance. This can lead to the two expressions being used interchangeably online.
Universal Credit legislation and current DWP guidance use good reason when considering a failure to comply with work-related requirements.
Regulation 105 of the Universal Credit Regulations 2013 deals specifically with the reduction period for a lowest-level sanction.
Why Is Attending Universal Credit Appointments Important?
Universal Credit appointments can form part of a claimant’s claimant commitment.
Depending on the person’s circumstances, appointments may be used to:
- Discuss work-search activity;
- Review work-related requirements;
- Consider changes in circumstances;
- Discuss health, caring or employment issues;
- Provide employment support; or
- Establish what the claimant needs to do next.
Appointments may take place at a Jobcentre, by telephone or through another agreed format.
Not every claimant has the same work-related requirements. A person’s claimant commitment should reflect their individual circumstances, including relevant health conditions, disabilities and caring responsibilities.
What Happens If a Mandatory Universal Credit Appointment Is Missed?
Missing an appointment does not itself prove that a sanction should be imposed.
The DWP should first consider whether:
- The appointment or requirement was mandatory
- The claimant failed to comply with it
- The claimant had a good reason for that failure
If the DWP accepts the good reason, the payment should not be reduced for that failure. If it does not, the claimant may receive a sanction.
Depending on the claimant’s conditionality group and the type of appointment, failing to attend can potentially lead to a lowest-level or low-level sanction.
How Common Are Universal Credit Sanctions for Missed Appointments in 2026?
Missed mandatory interviews continue to account for the overwhelming majority of adverse Universal Credit sanction decisions.
The latest DWP statistics, published in August 2026 and covering data to May 2026, show that 89.9% of adverse Universal Credit sanction decisions in the latest year related to failure to attend or participate in a mandatory interview.
The same release showed that in May 2026, 5.2% of Universal Credit claimants in conditionality regimes where sanctions could be applied were undergoing a sanction.
Those figures make prompt communication particularly important when an appointment cannot be attended.
Can a Claimant Avoid a Sanction After Missing an Appointment?
Yes. A missed appointment does not inevitably lead to a sanction.
If something makes it impossible to attend, the claimant should contact Universal Credit straight away where possible. The quickest route for most online claimants is a message through their Universal Credit journal.
The explanation should cover:
- Which appointment was missed
- The date and time
- Exactly what happened
- When the problem arose
- Why it prevented attendance or participation
- When the claimant became able to contact universal credit
- Any evidence available
- A request to rearrange the appointment.
If the problem is known about beforehand, contacting the work coach before the appointment is considerably better than simply failing to attend.
What Evidence Can Support a Good Reason?
Evidence can strengthen an explanation, but no single piece of evidence automatically guarantees that a reason will be accepted.
The DWP still considers the claimant’s circumstances as a whole.
| Situation | Evidence That May Help |
|---|---|
| Illness or treatment | Hospital information, appointment confirmation, medical correspondence or fit-note information |
| Mental health problem | Relevant medical or support information, where available |
| Bereavement | Funeral information or other relevant correspondence |
| Childcare emergency | School, nursery, childcare provider or medical communication |
| Caring emergency | Care provider, medical or support-worker correspondence |
| Court or tribunal | Summons, hearing notice or other official correspondence |
| Police-related issue | Custody documentation or other relevant official information |
| Domestic abuse or crime | Police, medical or specialist support information where appropriate |
| Transport disruption | Cancellation information, road closure, breakdown record or weather warning |
| Housing emergency | Council, landlord, housing provider, insurer or emergency-service correspondence |
| Work commitment | Employer communication, interview confirmation or rota |
| Technical failure | Outage notice, error screenshot or telephone records |
| Accessibility issue | Previous journal messages or relevant support information |
| DWP notification issue | Appointment to-do, journal messages, emails or call logs |
Evidence should explain the same event and timing described in the journal message rather than introducing a different reason afterwards.
12 Reasons That May Be Accepted for Missing a Universal Credit Appointment
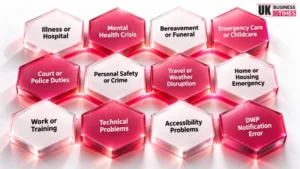
1. Unexpected Illness or Hospital Treatment
Unexpected illness or urgent medical treatment may amount to a good reason where it genuinely prevents attendance or participation.
Examples can include sudden illness, emergency treatment or a hospital appointment that directly clashes with the Universal Credit meeting.
GOV.UK specifically identifies unexpected illness and a conflicting hospital appointment as examples of situations that should be reported.
The important issue is not simply whether the claimant had a medical condition. The claimant should explain how the condition affected their ability to attend at that particular time.
If sickness becomes longer-term rather than a one-off problem, the rules surrounding long-term sick pay and Universal Credit may also become relevant, including fit notes, the claimant commitment and the Work Capability Assessment process.
2. Mental Health Problems or a Mental Health Crisis
A mental health problem can affect someone’s ability to travel, communicate, answer a scheduled telephone call, check their Universal Credit account or participate effectively in an appointment.
Anxiety, panic attacks, depression, trauma responses and other conditions affect individuals differently.
The claimant should therefore explain the functional impact at the time of the appointment, rather than assuming the diagnosis itself guarantees that the reason will be accepted.
Where available, relevant medical information, support-worker correspondence or earlier journal messages can help establish the circumstances.
If the issue repeatedly prevents the claimant meeting their existing requirements, they should also consider whether their claimant commitment still properly reflects their circumstances.
3. Bereavement or a Funeral
A death in the family or the loss of someone close may substantially affect a claimant’s ability to attend an appointment.
Relevant circumstances can include:
- Attending a funeral
- Making urgent funeral arrangements
- Supporting close relatives
- Dealing with practical matters after a death
- Experiencing severe distress following bereavement.
GOV.UK specifically gives a death in the family as an example of an emergency where a short pause or change to the claimant commitment may be possible.
Universal Credit should still be informed as soon as reasonably possible.
4. Emergency Caring or Childcare Responsibilities
Unexpected caring responsibilities may prevent attendance.
Examples include:
- A child suddenly becoming ill at school;
- An emergency collection from nursery;
- A childcare provider cancelling unexpectedly;
- An elderly relative requiring urgent assistance; or
- A disabled person the claimant cares for experiencing an emergency.
The claimant should explain why the situation was unexpected and why alternative arrangements were not reasonably available.
School messages, nursery notifications, care-provider communication or other dated records may help.
5. Court, Tribunal or Police-Related Obligations
A court hearing, tribunal appearance, jury service, police detention or similar unavoidable legal obligation may conflict directly with a Universal Credit appointment.
These situations should not be treated as automatically accepted in every case. The question remains whether the obligation genuinely prevented compliance and whether it could reasonably have been avoided or rearranged.
A court notice, tribunal correspondence, custody documentation or other official record can help establish what happened.
6. Domestic Abuse, Personal Safety or Being a Victim of Crime
Domestic abuse, violence or another serious incident involving personal safety may make attending or communicating with Universal Credit impossible or unsafe.
The claimant may be dealing with:
- Emergency accommodation;
- Police involvement;
- Urgent medical treatment;
- Immediate safety arrangements; or
- Support from a refuge or specialist organisation.
Universal Credit regulations and guidance recognise domestic violence and abuse as circumstances capable of affecting work-related requirements.
Only information necessary to explain the missed requirement should be provided.
7. Severe Travel Disruption, Weather or Transport Failure
Serious transport disruption may be a good reason if it genuinely prevents safe or reasonable travel to the appointment.
Examples can include:
- Widespread train cancellations;
- Cancelled buses with no reasonable alternative;
- Flooding;
- Dangerous weather;
- Unexpected major road closures;
- A vehicle breakdown; or
- A serious traffic incident.
The distinction between inconvenience and genuine inability to attend matters.
A minor delay may not be sufficient where reasonable alternatives existed. A complete cancellation of the only available route shortly before the appointment presents a much stronger explanation.
8. Serious Home or Housing Emergency
A sudden home emergency can require immediate attention and prevent attendance.
This could include:
- A fire;
- Serious flooding;
- A gas leak;
- Significant property damage;
- Sudden loss of accommodation;
- Emergency rehousing; or
- Imminent homelessness.
Current claimant-commitment guidance specifically identifies risk of homelessness as an emergency that can potentially justify a temporary pause or adjustment to requirements.
Council, landlord, housing-provider, insurer or emergency-service correspondence may provide useful supporting information.
9. Job Interview, Work or Training Commitments
A genuine employment-related clash can sometimes be relevant, particularly where an employer gives little notice.
Examples may include:
- An unexpected work shift;
- A job interview;
- Induction;
- Compulsory workplace activity; or
- Another employment-related commitment.
However, employment, education or training should not be assumed to override a mandatory Universal Credit appointment automatically.
Where the clash is known beforehand, the claimant should contact the work coach and ask for the Universal Credit appointment to be moved.
10. Technical Problems With a Phone or Online Appointment
A technical problem may prevent participation in a telephone or online appointment.
Examples include:
- An unexpected phone failure;
- A prolonged internet outage;
- Inability to access the universal credit account;
- A service outage; or
- Another technical failure occurring around the appointment time.
A vague statement that “the internet wasn’t working” may be difficult to assess.
A stronger explanation identifies when the outage began, how long it lasted, what the claimant tried to do and when another method of contact became available.
Relevant screenshots, outage notifications or telephone logs may help.
11. Disability, Language or Accessibility Problems
A disability, health condition, communication barrier or accessibility problem may affect whether the appointment can reasonably go ahead.
For example, a claimant may previously have explained that they require:
- An interpreter;
- Accessible premises;
- Additional communication support;
- A different appointment format; or
- Another reasonable adjustment.
If the required support is not available, the claimant should explain why that prevented meaningful participation.
Earlier journal messages showing that the issue had already been raised may be particularly useful.
12. DWP Scheduling or Notification Error
Sometimes the claimant may believe an appointment was missed because the information supplied by Universal Credit was incorrect, unclear or inconsistent.
Possible examples include:
- The appointment not appearing properly in the claimant’s account;
- Conflicting appointment times;
- Being told different appointment formats;
- A scheduled phone call arriving substantially outside the stated time; or
- An appointment being changed without the claimant seeing the update.
The claimant should preserve screenshots, appointment to-dos, messages, emails, text notifications and telephone records.
Rather than simply saying “the DWP made a mistake”, the journal message should identify exactly what the claimant was shown and how that differed from what later occurred.
Which Reasons Are More Likely to Be Rejected?
There is no automatic blacklist of unacceptable reasons, but some explanations are more difficult to establish as a good reason.
Waiting Several Days Before Making Contact
Late contact does not automatically destroy a genuine explanation, especially where the same emergency prevented communication.
However, unexplained silence for several days can make the circumstances more difficult to assess.
Giving Only a Vague Explanation
Statements such as:
- “Something came up”;
- “Family problems”;
- “I was busy”; or
- “Couldn’t make it”give the decision-maker very little information.
Dates, times and the practical effect of the problem are much more useful.
Making No Attempt to Rearrange the Appointment
For some sanction types, contacting Universal Credit and complying with a new appointment is particularly important because the sanction period can continue until compliance takes place.
Repeatedly Relying on an Issue That Has Never Been Reported
If the same health, caring, disability, transport or digital-access problem keeps preventing compliance, the claimant may need to report a change in circumstances or ask for the claimant commitment to be reconsidered.
Repeatedly explaining individual missed appointments without addressing the underlying problem can create difficulties.
Confusing Inconvenience With Inability to Attend
Something being difficult or inconvenient does not necessarily mean there was a good reason for non-attendance.
For example, ordinary traffic or a routine personal commitment may be treated differently from a motorway closure, medical emergency or unavoidable legal obligation.
What Should a Claimant Write in the Universal Credit Journal?
A useful journal message should be brief but specific.
Weak Example
I couldn’t come today because something came up. Sorry.
This gives almost no information about why the requirement could not be met.
Stronger Example
I was due to attend my Jobcentre appointment at 10:00am today. At 9:15am my child’s school called to say they were unwell and had to be collected immediately.
I had no alternative person available to collect or care for them, so I could not attend the appointment. I have the school’s message if evidence is needed. Please could the appointment be rearranged?
The second version establishes the appointment, timing, unexpected event, direct effect, evidence and intention to rearrange.
Copyable Universal Credit Missed Appointment Template
A claimant can adapt the following wording rather than submitting a vague explanation:
I was due to attend my Universal Credit appointment on [date] at [time]. I was unable to attend because [briefly explain what happened].
The problem began at approximately [time/date] and prevented me attending because [explain the direct effect]. I contacted Universal Credit as soon as I was reasonably able to do so.
I can provide [evidence, if available]. Please record my explanation and let me know when the appointment can be rearranged.
Claimants should only include information that is accurate and relevant to their actual circumstances.
How Long Can a Universal Credit Sanction Last?
Universal Credit currently has four levels of sanction.
For claimants aged 18 or over, the main sanction periods can be summarised as follows:
| Sanction Level | Typical First Sanction | Repeat Sanction |
|---|---|---|
| Lowest | Continues until the relevant compliance condition is met | No separate fixed repeat period |
| Low | Time until compliance + usually 7 fixed days | Fixed period can increase to 14 and then 28 days |
| Medium | 28 days | 91 days in relevant repeat cases |
| High | 91 days | Up to 182 days in relevant repeat cases |
A lowest-level sanction can run from the date of the missed requirement until the day before the claimant meets the relevant compliance condition, such as arranging another appointment, subject to the applicable rules.
For low-level sanctions, the compliance period may be followed by additional fixed days. Repeat low-level failures within the relevant period can increase the fixed part from 7 to 14 and then 28 days.
Medium-level and high-level sanctions have longer fixed periods. Different rules apply to claimants aged 16 or 17 and to some specific employment situations.
The latest Universal Credit benefit rates for 2026/27 are also relevant because sanctions normally reduce the standard allowance rather than automatically removing every Universal Credit element.
Current GOV.UK guidance says most sanctions reduce the applicable standard allowance at 100% of the daily rate, although a 40% rate applies in certain circumstances. Amounts for children or housing can continue to be paid.
Can Several Sanctions Run Together?
Universal Credit does not normally apply two sanction reductions at exactly the same time. Reduction periods can instead run consecutively.
Citizens Advice states that the maximum period for a single sanction is 182 days, while multiple sanctions running consecutively can produce an outstanding reduction period of up to 1,095 days.
The 1,095-day ceiling is also reflected in regulation 101 of the Universal Credit Regulations framework.
How Can a Universal Credit Sanction Be Challenged?
A claimant who believes a sanction is wrong can ask the DWP to reconsider the decision.
The first formal stage is a Mandatory Reconsideration.
The claimant should explain:
- Which decision they disagree with;
- Why they had a good reason;
- Which facts the decision-maker overlooked or misunderstood; and
- What evidence supports their explanation.
A Mandatory Reconsideration should normally be requested within one month of the decision date, although late applications can sometimes be accepted where there is a good reason for the delay.
If the DWP does not change the decision, the claimant can normally appeal to the independent Social Security and Child Support Tribunal.
What Percentage of Universal Credit Sanction Appeals Succeed?
This needs careful interpretation because different figures refer to different populations and periods.
Recent research involving Public Law Project and Central England Law Centre found that 86% of sanction cases that reached the appeal stage were overturned. That figure was also cited during evidence to Parliament in June 2026.
Older official DWP figures showed that 81% of sanction appeals were successful for claimants. That historical figure continues to be cited by specialist welfare-rights organisations.
These percentages do not mean that 81% or 86% of all Universal Credit sanctions are overturned. They refer specifically to cases that were challenged far enough to reach the relevant appeal stage.
That distinction matters because many sanction decisions are never appealed.
What About the 14% Mandatory Reconsideration Figure?
Some Universal Credit resources quote figures of around 14% for successful Mandatory Reconsiderations.
That statistic should not automatically be treated as a current, sanction-specific national rate. Some widely circulated UC Mandatory Reconsideration figures relate particularly to capability-for-work decisions rather than solely to sanctions.
There is also an important data limitation: the DWP’s current Universal Credit sanctions methodology states that it does not yet have reliable full-service data for Mandatory Reconsiderations and appeals, and warns that appeal information may be under-recorded.
For that reason, the safest interpretation is:
- Mandatory reconsideration is still the normal first formal challenge;
- An unsuccessful mandatory reconsideration does not mean an appeal will necessarily fail;
- Appeal-stage studies show substantially better outcomes among claimants who actually reach that stage; and
- Historic or research-based success rates should not be presented as a guaranteed current national probability.
Should a Claimant Give Up After Losing a Mandatory Reconsideration?
No conclusion should be drawn solely from the Mandatory Reconsideration refusal.
An independent tribunal is separate from the DWP and can consider the evidence and circumstances again.
The relatively high historic and research-based success rates among sanction cases reaching appeal demonstrate why a claimant who still believes the decision is wrong may wish to continue the challenge rather than treating the Mandatory Reconsideration decision as final.
What If the Sanction Leaves the Claimant Without Enough Money?
A claimant who cannot afford essential costs because of a sanction may be able to apply for a Universal Credit hardship payment.
Current GOV.UK guidance identifies essential needs such as:
- Rent;
- Heating;
- Food; and
- Hygiene needs.
Hardship payments generally have to be repaid through later Universal Credit payments.
Does This Apply in Scotland and Northern Ireland?
The main GOV.UK Universal Credit sanctions guidance applies to England, Scotland and Wales.
Claimants in Scotland remain within the DWP Universal Credit system for these sanction rules, although separate Scottish crisis-support schemes may be available.
Northern Ireland administers Universal Credit separately through the Department for Communities and has its own regulations and administrative arrangements.
The system still uses the concept of having a good reason, and sanction levels and durations are broadly similar, but a claimant in Northern Ireland should use the Northern Ireland procedures and support routes.
What About Holidays, Religious Observance or Other Commitments?
These circumstances should not be described as automatically acceptable or automatically unacceptable.
Examples include:
- Holidays
- Travel
- Religious observance
- Education
- Reservist or military commitments
- Other professional or personal obligations
The circumstances of the conflict still matter.
Where the claimant knows about it in advance, they should contact Universal Credit before the appointment and ask whether the appointment or requirement can be changed.
Simply deciding that another commitment is more convenient is much less persuasive than demonstrating that the claimant could not reasonably comply with both obligations.
How Should Evidence Be Submitted?
Where Universal Credit asks for supporting information, the claimant should make sure that the evidence is clear and directly linked to the explanation given.
Useful practices include:
- Keeping screenshots or copies
- Making dates and times visible
- Explaining what each document shows
- Keeping copies of journal messages
- Recording attempted telephone contact
- Retaining the original appointment notification
A large volume of unrelated evidence is not necessarily stronger than one or two documents that clearly prove the timing and circumstances.
How Can Future Missed Appointments Be Avoided?
Unexpected emergencies cannot always be prevented, but several administrative problems can.
Claimants can reduce the risk by:
- Checking the universal credit journal regularly
- Adding confirmed appointments to a calendar immediately
- Checking whether an appointment is mandatory
- Keeping telephone and email details current
- Reporting changes in circumstances promptly
- Discussing recurring health or caring problems with the work coach
- Requesting reasonable adjustments where required
- Notifying universal credit of known appointment clashes in advance
- Keeping a simple record of important messages and evidence.
A claimant whose circumstances have changed significantly should consider whether the claimant commitment itself needs to be updated rather than repeatedly struggling with requirements that no longer reflect their situation.
Conclusion
There is no guaranteed list of acceptable reasons for missing a Universal Credit appointment. The central question is whether the claimant had a good reason for failing to attend or participate.
Unexpected illness, hospital treatment, bereavement, emergencies, caring responsibilities, severe transport disruption and accessibility problems can all be relevant, but circumstances and communication matter.
Claimants should explain exactly what happened, contact Universal Credit as soon as reasonably possible, keep useful evidence and ask to rearrange the appointment.
If a sanction is imposed despite a genuine good reason, Mandatory Reconsideration and, where necessary, an independent tribunal appeal remain available.
FAQs
What Are Acceptable Reasons for Missing a Universal Credit Appointment?
There is no fixed list that guarantees acceptance.
Unexpected illness, hospital treatment, bereavement, domestic emergencies, serious caring responsibilities, transport disruption and other unavoidable circumstances may amount to a good reason depending on the facts.
What’s the Difference Between “Good Reason” and “Good Cause”?
“Good reason” is the terminology normally used for Universal Credit. “Good cause” is commonly encountered in older or legacy-benefit terminology.
The expressions are sometimes used interchangeably online, but “good reason” is more accurate when discussing current Universal Credit sanctions.
How Long Does a Claimant Have to Report a Missed Universal Credit Appointment?
There is no advantage in waiting. GOV.UK tells claimants who cannot meet their commitments to contact Universal Credit straight away.
Where advance warning is impossible, the claimant should make contact as soon as reasonably possible and explain why any delay itself occurred.
Will Universal Credit Stop After One Missed Appointment?
Not automatically. A mandatory appointment missed without an accepted good reason may lead to a sanction, but the outcome and duration depend on the claimant’s work-related requirements and sanction level.
What Happens If Someone Simply Forgets a Universal Credit Appointment?
Forgetting does not guarantee that the entire Universal Credit claim will stop, but forgetting alone may not amount to a good reason.
The claimant should contact Universal Credit immediately, explain the circumstances honestly and ask for another appointment.
Can Mental Health Be a Good Reason for Missing an Appointment?
Yes. A mental health problem may amount to a good reason where it genuinely affects the person’s ability to travel, communicate or participate. The DWP should consider the effect of the claimant’s circumstances rather than relying solely on the name of the condition.
Does a Claimant Need Evidence for Every Missed Appointment?
Not necessarily. Evidence can strengthen an explanation, but the DWP considers all the circumstances. Where relevant evidence exists, retaining and providing it can make the sequence of events easier to establish.
Can a Universal Credit Sanction Be Appealed?
Yes. A claimant can normally first request a Mandatory Reconsideration. If the decision is not changed, an appeal can then be made to an independent tribunal.
What Percentage of Universal Credit Sanction Appeals Succeed?
Older DWP figures showed an 81% claimant success rate among sanction cases reaching appeal, while more recent Public Law Project/Central England Law Centre research reported an 86% overturn rate among cases reaching that stage.
These are appeal-stage figures, not the percentage of all sanctions that are overturned, and the DWP currently warns that full-service sanction challenge statistics are incomplete.
How Long Can a Universal Credit Sanction Last?
The duration depends on the sanction level and previous sanction history. A high-level repeat sanction can last up to 182 days. Multiple sanction periods can run consecutively, subject to an overall outstanding reduction-period limit of 1,095 days.